The Rivera Advantage · Military moves
Military relocation to Augusta & the CSRA.
PCSing to Fort Gordon (formerly Fort Eisenhower)?
New orders. A new community. A home that fits your next chapter. Let's approach your PCS move with a plan built around your timing, budget, and priorities.
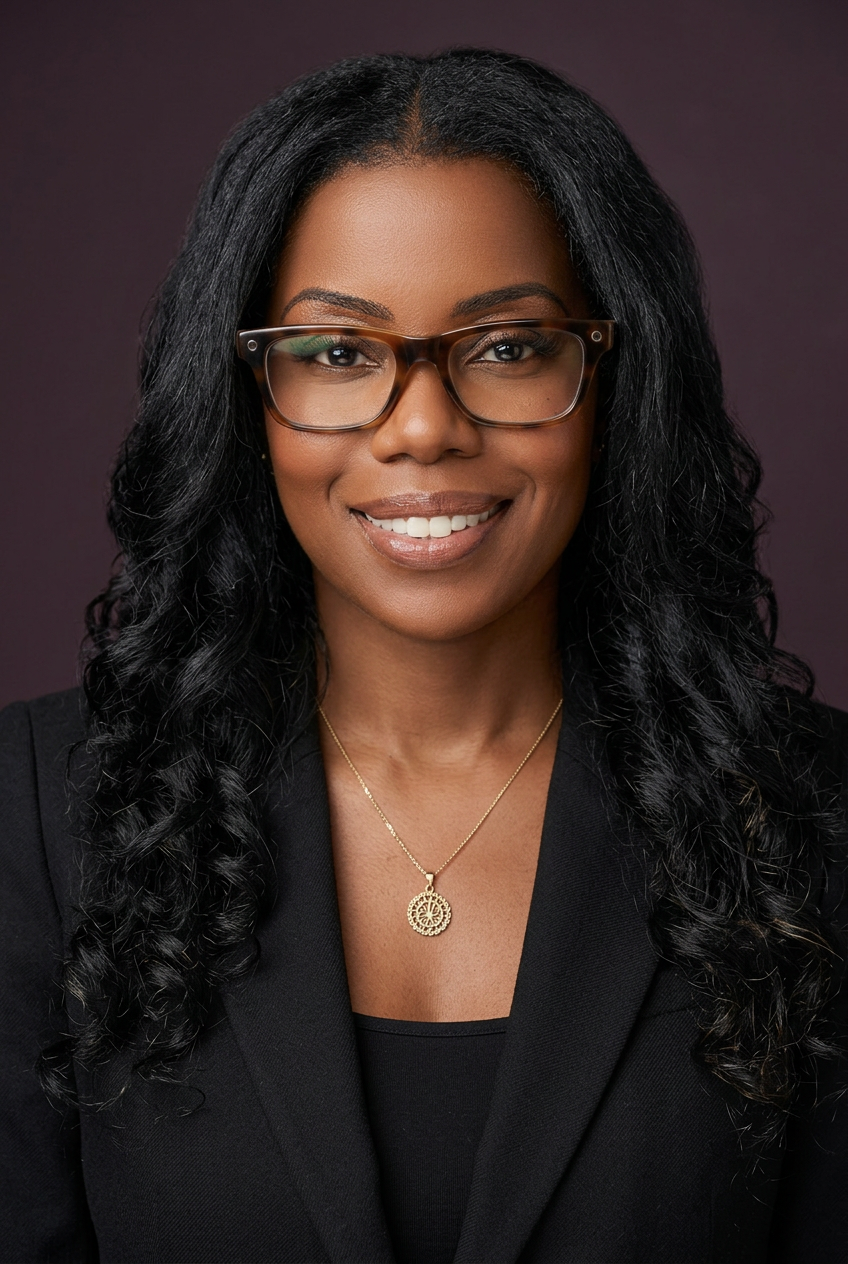
A fellow veteran in your corner
Your orders set the timeline. Your goals set the direction.
I'm Tahirah Rivera, an Air Force veteran and REALTOR® with Realty ONE Group Visionaries. I help buyers explore Augusta and the surrounding CSRA, with a focus on the details that matter to your move. My background in mortgage lending brings another perspective to the questions we discuss with your chosen lender.
Whether you're buying your first home or relocating again, we'll work through your priorities before narrowing the search.
Your PCS home-search plan
Start with the decisions that matter.
- 01
Set your arrival window
Share your report date, expected arrival, and any housing deadlines. Plan temporary accommodation if your purchase timeline doesn't align with your move.
- 02
Build a realistic monthly budget
Discuss financing with your lender. Compare the full payment, taxes, insurance, possible HOA fees, closing costs, and a reserve for maintenance—not just the purchase price.
- 03
Compare locations around your routine
Consider Augusta, Grovetown, Evans, Martinez, and Hephzibah. Check your actual gate or duty location, commute at relevant times, and the services you use. Verify school assignments directly with the district.
- 04
Plan tours and due diligence
Discuss available in-person or remote viewing options, inspections, and contract deadlines. Ask your lender and closing professionals how your availability and PCS timing affect the process.
VA homebuyer essentials
Know what to ask your lender.
Eligibility & your COE
A Certificate of Eligibility helps establish your VA benefit eligibility. It is not loan approval. Your lender will also review credit, income, and the other requirements for your purchase.
Costs & entitlement
Ask about available entitlement, any required down payment, closing costs, and the VA funding fee. Some borrowers qualify for a funding-fee exemption. Your lender can explain what applies to you.
Occupancy & condition
VA purchase loans are intended for a primary residence and have occupancy and property requirements. Discuss deployment or PCS circumstances with your lender. An appraisal does not replace a home inspection.
This is general real estate information, not legal, tax, or lending advice. VA eligibility, financing terms, and approval are determined by the VA and your lender. No loan approval, rate, or terms are guaranteed.
Official resources
Representation with intention
Let's talk about your next move.